Start with a documentAnyone weighing a review: a fund partner, a board member or an adviser. You can test it on a company you know, without involving management or sharing confidential company information.
The decision
The potential strategic options, from public information only — see a sample review.
What you receive
The potential strategic options, and what each needs to be valued.
Start with a documentA company ready to share its own information under a mutual confidentiality agreement, and to name the decision the document should support.
The decision
The one named decision the document supports, with the company's own information. Before you send confidential company information, we sign a mutual confidentiality agreement.
What you receive
The strategic options, each valued on the company's own information.
The requirements each would place on the company.
The company-information request for the review.
Fee and time
20% of the review's fee, credited against it
8–12 pages
About ten days after the information request is complete
After complete information
If you commission the review within thirty days of this document's delivery, we deduct its fee from the payment due on commissioning.
Venture-backed companiesA pre-revenue or seed venture company, or any company choosing its market and business before a round; or a venture fund commissioning for one of its companies.
The decision
Which choice of market and business best supports the next funding round?
What you receive
The decision document, then the full review, as a draft and then the final.
The market sized three ways.
The competitive landscape by type.
Comparable companies and transactions, with averages and deal counts.
The potential buyers and investors by name.
The recommended strategy with its playbook.
The round model, valuing each strategic option to the existing shareholders after the round.
The workbook behind every figure.
Fee and time
£15,000 excluding VAT
About 40 pages
Final within two weeks
After complete information
Prices in pounds sterling, exclude VAT.
Illustrative sample
A venture example follows the first venture review on the current software.
Scope and exclusions
The strategic options: Three to five market and business choices, valued to the existing shareholders after the round: the proceeds and the multiple on the round's money.
It excludes: Customer and pricing evidence and detailed competitive analysis, which are in the Growth and Funding Review; the full range of strategic options valued on the shareholders' return, which is the Shareholder Return Review.
The information needed
The company's own information and the public record. No interviews. Public and sector evidence first.
Venture-backed companiesA revenue-stage venture company spending cash to grow, typically at Series A or B; and its investors.
The decision
Which growth path, and the financing each needs?
What you receive
The decision document, then the full review, as a draft and then the final.
Everything in the Market and Funding Review.
Customer and pricing evidence, competitor profiles in depth, and the runway and dilution of each strategic option, valued to the shareholders after the financing it needs.
Fee and time
£30,000 excluding VAT
About 70 pages
Final within three weeks
After complete information
Prices in pounds sterling, exclude VAT.
Illustrative sample
A venture example follows the first venture review on the current software.
Scope and exclusions
The strategic options: Four to six growth paths, valued with burn, runway and the next pre-money as outputs.
It excludes: The full range of strategic options valued on the shareholders' return at each exit, which is the Shareholder Return Review.
The information needed
The company's own information and the public record, with customer and pricing evidence from the company's own sales, pricing and retention records. No interviews.
PE-backed, private or public companiesA private-equity-backed, privately owned or listed company, at mid-hold or before an exit.
The decision
Which strategy and which exit route most raise the return to the shareholders; for a listed company, which raises the value per share at a target date?
What you receive
The decision document, then the full review, as a draft and then the final.
The strategic options open to the company, those the evidence supports valued on one basis.
A reason recorded for every option set aside.
Each valued on the shareholders' return at every exit open to them, or on the value per share at a target date for a listed company.
The recommended strategy, with the evidence behind it and a detailed playbook.
For each, the conditions it must meet and the information that would settle it.
The workbook behind every figure.
Fee and time
£50,000 excluding VAT
About 120 pages
Final within four weeks
After complete information
Prices in pounds sterling, exclude VAT.
Illustrative sample
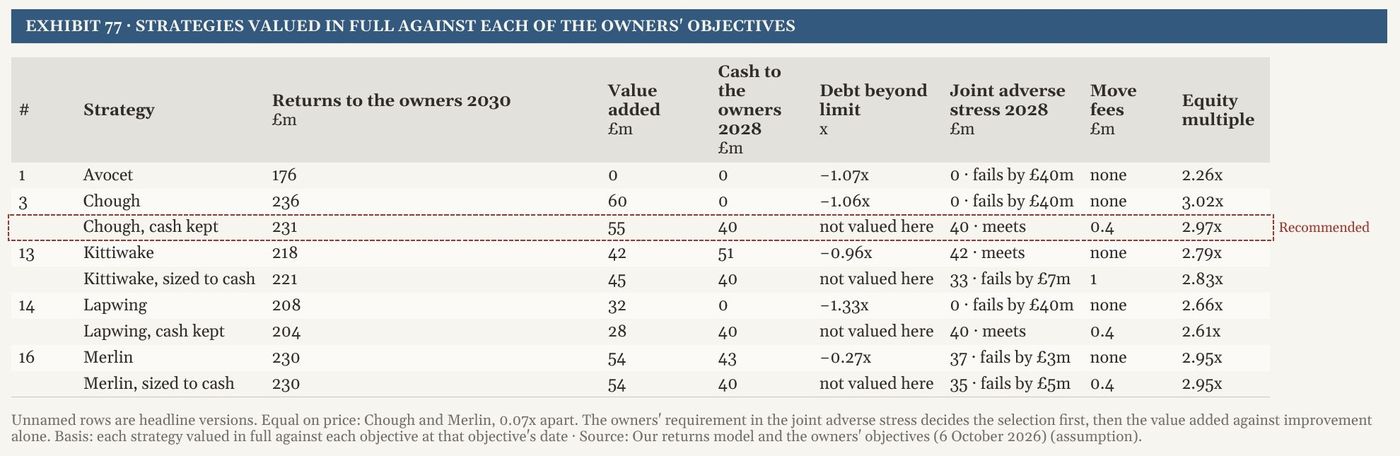
Exhibit 77: the strategies valued in full against each of the owners' objectives, page 138 of the test company's review
The strategic options: Levers, divisional moves, acquisitions, partnerships, funding, cash and exit forms, each valued on the leveraged return to the shareholders; for a listed company, value per share at a target date.
It excludes: Transaction work and implementation, which stay the company's own; divisional analysis and reviews of an acquisition target or partner, which are Additional Modules.
The information needed
The company's own information first, then peer multiples, precedent transactions and the public record. No interviews.
PE-backed, private or public companiesA private-equity-backed, privately owned or listed company, where a fund or a board is commissioning for a decision at a set board date.
The decision
The Shareholder Return Review's question, benchmarked against named peers and taken to the board.
What you receive
Everything in the Shareholder Return Review.
A benchmark against named peers on their disclosed figures, put on one basis.
The review in board-ready form, with one round of the board's substantive comments taken into the final.
Greater analysis of each business unit.
Fee and time
£75,000 excluding VAT
About 180 pages
Final in five to six weeks
After complete information
Prices in pounds sterling, exclude VAT.
Scope and exclusions
It adds: peer benchmarking, the review in board-ready form with one round of the board's substantive comments taken into the final, and greater analysis of each business unit.
Ordinary comments on the draft are part of every review; the Extended Shareholder Return Review takes one round of the board's substantive comments into the final.
The strategic options: The same, with a normalised peer benchmark on disclosed data.
It excludes: As the Shareholder Return Review.
The information needed
As the Shareholder Return Review, with the peers' disclosed figures.
Additional productsA company with an existing review, for a division, an acquisition target or a partner, or for an update.
The decision
Divisional analysis; an M&A target or partner review; an updated strategic review. On an existing review's information. Strategic analysis, never due diligence on a target.
Additional productsA fund that wants each of its portfolio companies reviewed on one standard.
The decision
The Continuing Review across the portfolio companies of a fund, each board receiving its own review, with the evidence and the format adapted to the fund.
Strategic decision support: the review helps decide which option merits due-diligence spend. It is not commercial due diligence, includes no customer interviews and carries no reliance letter. The illustrative samples are pages from the method's test company, a fictional UK business.
For the same company, the fee paid for a review is credited in full against the next review up the ladder commissioned within twelve months: the Market and Funding Review, then the Growth and Funding Review, then the Shareholder Return Review, then the Extended Shareholder Return Review. The full engagement terms →How an engagement runs →
Tell us the company and the question in front of its shareholders.